Medicare guidance, in plain language
Medicare decisions with quiet confidence.
We help people turning 65 — and everyone already on Medicare — understand their choices, avoid the permanent penalties, and pick coverage that actually fits.
You don't have to figure this out alone. John walks you through it — pre-planning, enrollment, and the review every year after — one decision at a time.
- 1 Pre-planning. What to decide before 65, and when — mapped to your dates.
- 2 Enrollment. Your choices explained in plain language, then the paperwork handled.
- 3 Every year after. A review each fall, so what fit last year still fits this one.
Meet your advisor
John Smith
John Smith is with RR Medicare, where he helps individuals navigate their Medicare options. He focuses on providing clear, straightforward guidance so people can make informed decisions about their coverage. Clients working with John can expect a respectful, patient approach to understanding their choices.
How it works
A calm, three-step path.
John carries the deadlines and the fine print. You bring your questions.
Discovery
A short, no-pressure conversation about your health coverage, your timeline, and your budget.
Your options
We walk through the choices that fit your situation and explain each trade-off — in plain language.
Decide & review
You choose what fits, we handle the details, and we review it together every year at enrollment time.
Who I serve
Built for every stage of Medicare.
Turning 65
Your first enrollment window is seven months wide — we map the dates and the choices before it opens.
Working past 65
Employer coverage, Medicare timing, and the penalties to avoid, sorted out before you retire.
Already on Medicare
Reviewing your coverage as your health, your budget, and the plan options change each year.
How I help
Built around your Medicare decisions.
Enrollment timing
Coverage choices
Prescription coverage
Social Security timing
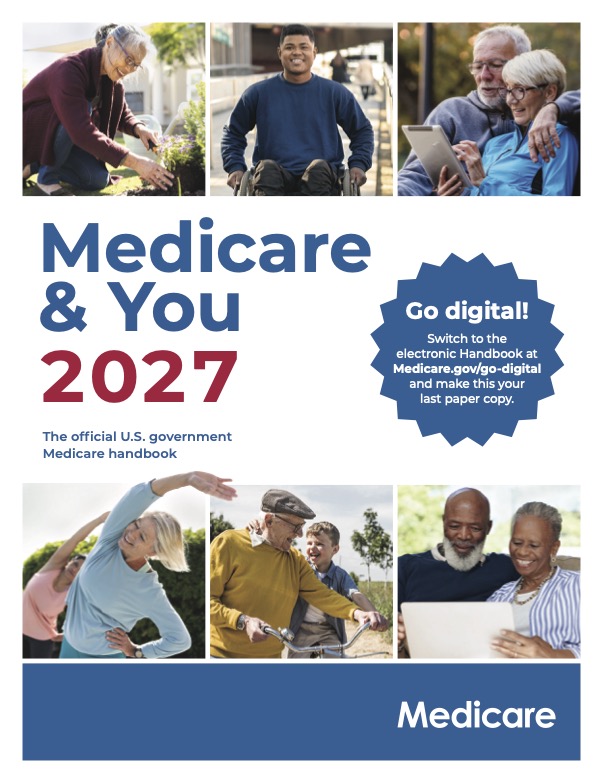
Free download
Medicare's own handbook, explained by the people who run the program.
“Medicare & You” is the government's own guide to every part of the program — coverage, costs, and the deadlines that can carry lasting penalties. Download it here, then bring your questions to the conversation.
Also available free at Medicare.gov.
Your dates
Curious when your own window opens?
Ten seconds, from your birth month. John keeps track of it either way.
When is my enrollment window?
The Medicare year
Four windows. Know yours.
You don't need to memorize these. John tracks them for you — this is just so nothing catches you off guard.
Your Initial Enrollment Period — check whether you qualify to delay without penalties.
Check your dates →Annual Enrollment: eligible beneficiaries can join, switch, or drop Advantage or drug plans for January 1.
How it works →Advantage members get one more adjustment window.
About Advantage →Special Enrollment Periods open when life changes — usually briefly.
The exceptions →Part D penalties can apply after 63 consecutive days without creditable drug coverage and use the national base beneficiary premium. Extra Help is an exception; qualifying Special Enrollment Periods and Medicare Savings Programs can prevent Part B penalties. Check Medicare.gov for the rules.
A quick gut-check
Will you pay more for Medicare?
Higher-income households pay an extra Medicare premium called IRMAA. It is set by the tax return you filed two years ago, and one dollar over a threshold moves you a whole bracket. Drag the slider to see where you land. It is a simple estimate — your full picture lives in the Medicare Center, where you can go deeper and save your progress.
Explore your Medicare CenterIllustrative only — uses the 2026 IRMAA brackets, per enrolled person. Not advice.
From our insights
Plain-English Medicare & retirement guidance.
Can Your Retirement Income Cover Real Life?
Could your retirement income cover an ordinary month, including health care? Your savings balance is a startin...
Read article →
It's Game Time
Football season is all about preparation, adjustments and staying focused on the goal. I believe retirement pl...
Read article →
Don't Derail Your Retirement
How would your retirement plan respond if you or your spouse needed long-term care? Explore four common planni...
Read article →What to expect
How working with us feels.
No pressure. Ever.
You will never be rushed toward a plan. We explain, you decide — on your timeline.
Trade-offs, out loud.
Every option comes with its costs and its catches stated plainly, before you choose.
A relationship, not a sale.
Plans change every year. We review yours every fall, so it keeps fitting.
Twice-Monthly Newsletter
Two concise emails per month: Medicare deadlines to watch, plain-language explainers, and decision checklists.
Good to know
Questions, answered.
When do I need to sign up for Medicare? +
Most people have a seven-month window around their 65th birthday — three months before, the birthday month, and three months after. Late penalties can apply, but qualifying coverage and assistance programs may provide exceptions. Check your situation before the window opens.
I am still working at 65 — do I have to enroll? +
It depends on your employer coverage and its size, and the rules around HSA contributions add a twist. This is one of the most common places people get tripped up; a short conversation sorts out your specific situation.
What is the difference between a Medicare Supplement and Medicare Advantage? +
They are two very different ways to cover what Original Medicare does not — one trades a higher premium for predictable costs, the other a lower premium for networks and cost-sharing. We walk through the real trade-offs for your health and budget, in plain language.
What does it cost to talk? +
The consultation is free and there is no obligation. We will explain how we work, and how we are compensated, before you decide anything.
Is this official Medicare information? +
No — this is an independent educational site, not the government. For information on every option available to you, contact Medicare.gov or 1-800-MEDICARE.
Get started
Let's talk about your Medicare options.
A short, no-pressure conversation — and a clear next step before your deadlines arrive.